Skip to content

Insights

Private Money In. Bank Money Out: The Refinance Exit Strategy

The two kinds of capital aren't competitors on most transactions. They're consecutive stages of the same deal.

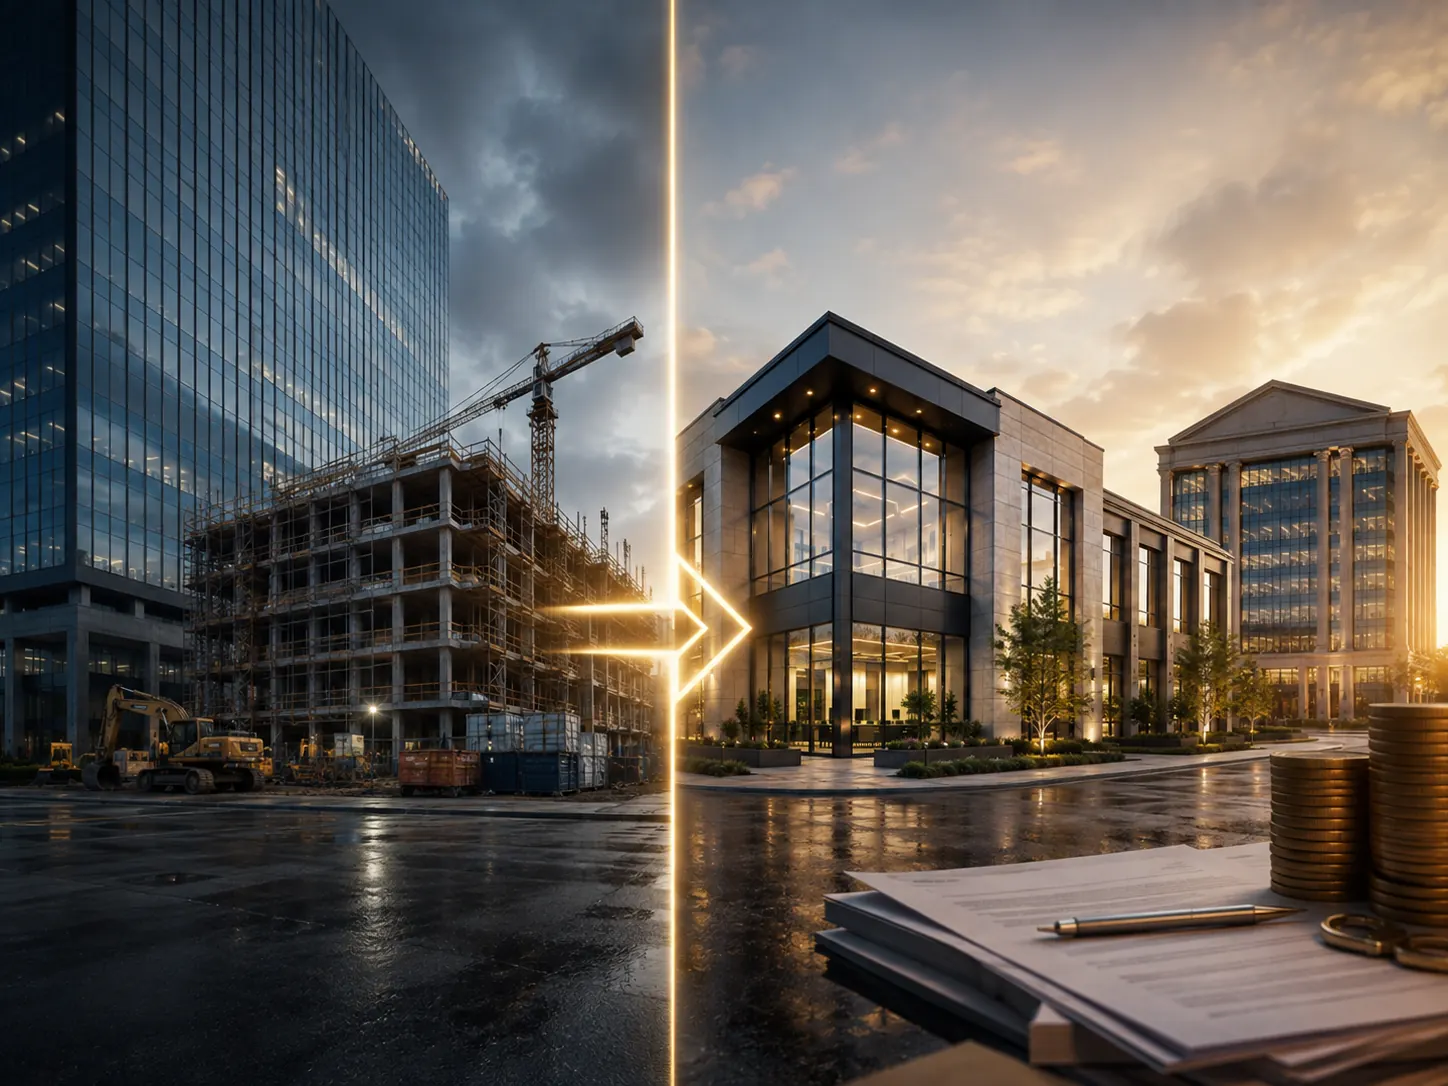
A building under construction on one side, the finished and stabilised property on the other, with an arrow running between them.

Why the sequence works

A property that can't be bank-financed today often can be in a year — once it's leased, once the work is done, once there's an operating history to underwrite. The obstacle isn't the asset, it's its current condition.

Private capital funds the phase where the property is being changed. Bank capital funds the phase where it's stable and boring. Using either one for the other phase is where the cost shows up.

Design the exit before you take the entrance

The refinance has to be sized on stabilised income against rates and terms available at that time, not on the ones you'd prefer. If the permanent loan won't cover the short-term balance plus costs, the gap comes out of your pocket — and you'll know that going in or you'll find out at maturity.

Coverage is the constraint that usually binds. Work out the debt service the property can support first, then let that determine how much permanent debt exists to pay off.

Seasoning and documentation

Conventional lenders generally want an operating history before they'll underwrite a repositioned property, and they want leases, statements and a clean title picture to go with it. Some measure value from the current appraisal; some measure from what you paid.

That's a real constraint on when the exit can happen, and it belongs in the plan from the beginning rather than being discovered when the short-term loan is sixty days from maturity.

Leave yourself room

Build in more time than the plan needs. Lease-up runs late, contractors run late, appraisals run late, and a maturity date doesn't. An extension option costs something; needing one and not having it costs considerably more.

The strategy is sound. It just has to be executed against a calendar with slack in it.

General information about commercial real estate financing. It is not legal, tax, accounting or investment advice, and it does not describe the terms available on any particular transaction.

A good deal shouldn't die waiting on a bank.

Tell us about the transaction. You'll get a straight answer about whether it fits — including a fast no if it doesn't.

When Banks Stall, Maverick Moves.

Submitting deal information does not constitute an application for credit. Nothing here is an approval, a denial, a commitment to lend, or an offer of credit. All financing is subject to underwriting, third-party reports and final credit approval.

Get My Deal Done