Skip to content

Insights

Financing the Fix: What Makes a Value-Add Deal Fundable

On a value-add transaction the collateral is partly a building and partly a business plan. Both get underwritten.

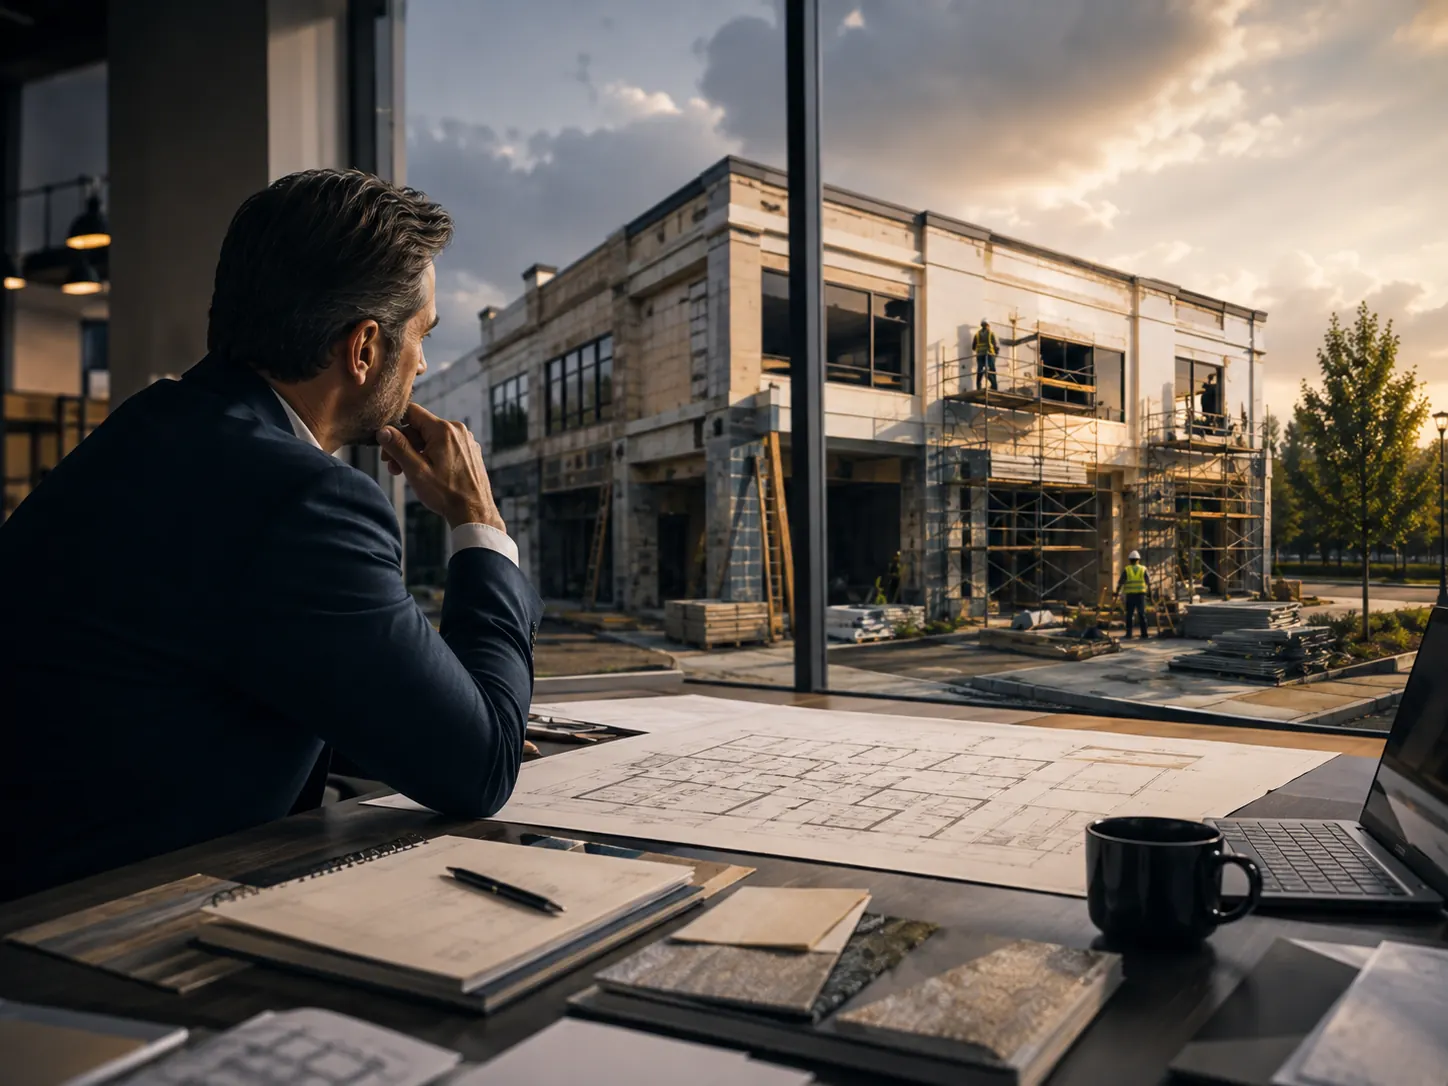
An investor at a desk of renovation drawings, watching crews work on the scaffolded building outside the window.

The scope has to be a document, not a description

"It needs about eighty thousand of work" is a sentence. A line-item budget with quantities, a contractor attached to it, and a sequence is a scope. The second one can be funded in draws; the first one can't be funded at all.

The budget is also where most deals get repriced late. Contingency isn't padding — it's the difference between a draw schedule that survives contact with the property and one that runs out three months in.

As-is versus after-repair

Two values matter, and they answer different questions. As-is value supports what you're borrowing at closing. After-repair value supports what the total facility can be, and it's the one that determines whether the exit works.

Leverage measured against cost tells you how much of your own capital stays in the deal. Leverage measured against value tells you how much room there is if the market moves. A lender looks at both, and so should you.

Draws are a schedule, not a formality

Renovation money is released against completed work, usually with an inspection. That means you carry each stage before you're reimbursed for it, and the reimbursement takes as long as the inspection takes.

Deals stall here more often than they stall at underwriting. Knowing your draw cycle before you start is the difference between a project that keeps moving and one that idles while the interest clock runs.

The exit is part of the underwriting

A renovation loan is short-term by design, so the question of what pays it off is not a detail to be sorted out later. If the plan is a sale, the after-repair value has to survive a real market, not an optimistic one. If the plan is a refinance, the stabilised income has to support the permanent debt at rates that exist today.

A deal without a defined exit isn't a value-add transaction. It's a bet with a maturity date on it.

General information about commercial real estate financing. It is not legal, tax, accounting or investment advice, and it does not describe the terms available on any particular transaction.

A good deal shouldn't die waiting on a bank.

Tell us about the transaction. You'll get a straight answer about whether it fits — including a fast no if it doesn't.

When Banks Stall, Maverick Moves.

Submitting deal information does not constitute an application for credit. Nothing here is an approval, a denial, a commitment to lend, or an offer of credit. All financing is subject to underwriting, third-party reports and final credit approval.

Get My Deal Done