Skip to content

Insights

Can the Property Pay for the Loan? That's the DSCR Question

DSCR is net operating income divided by annual debt service. Simple arithmetic — and every dispute about it happens above the division line.

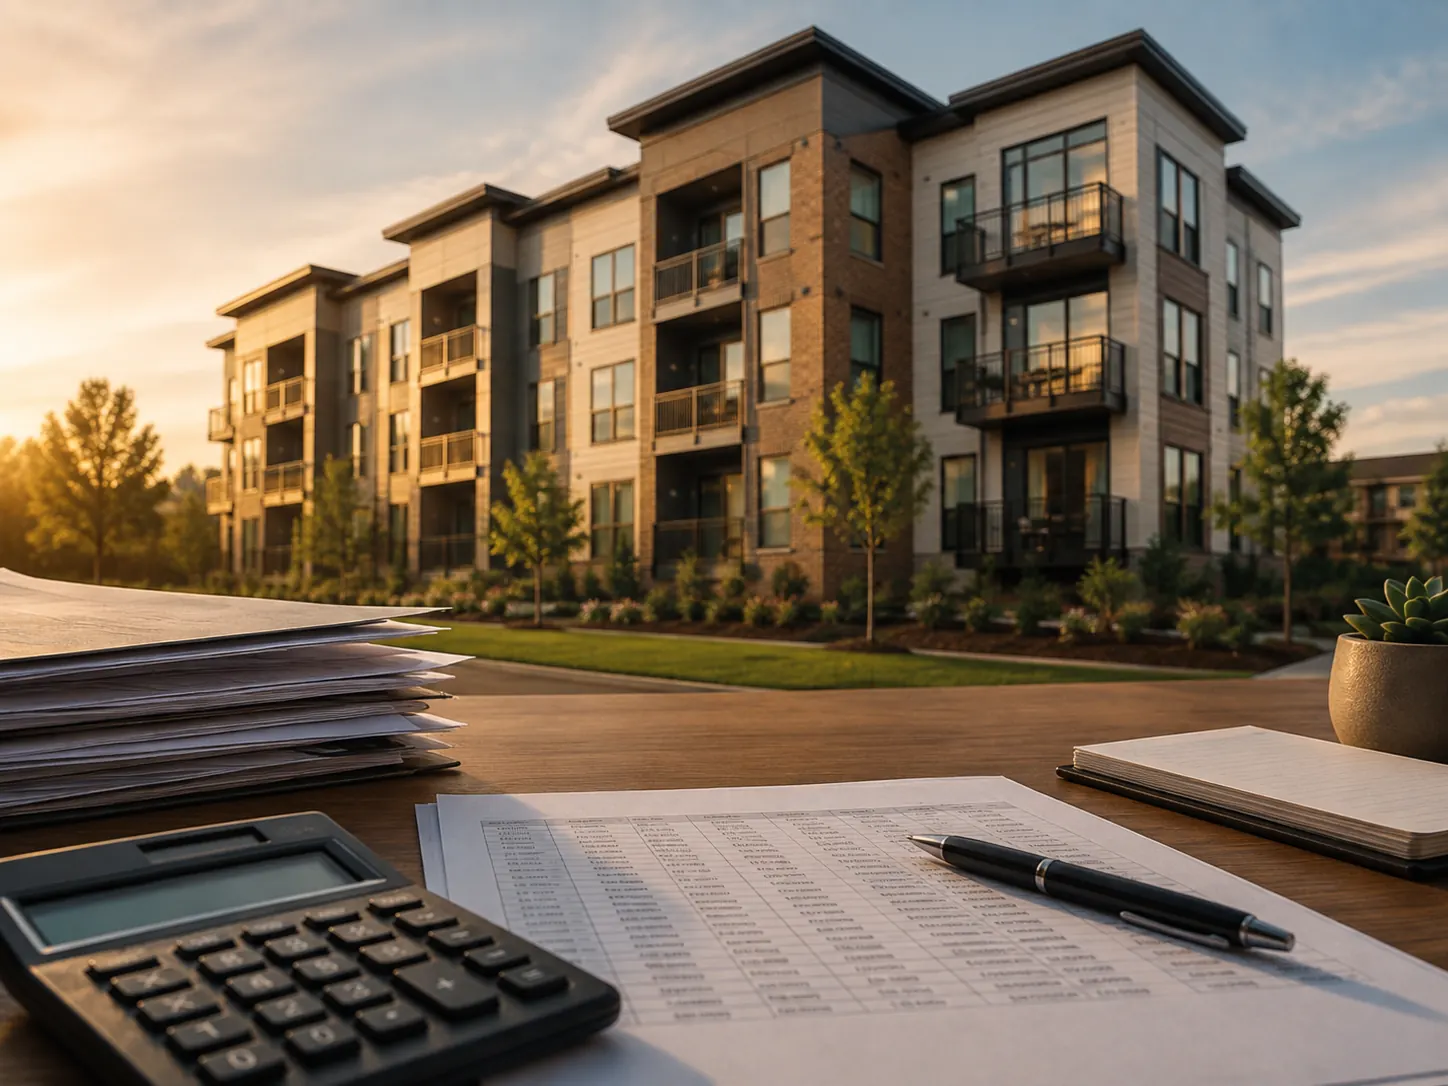
A rent roll and a calculator on a desk, with the apartment building the numbers belong to standing beyond it.

What the ratio is telling you

A DSCR of 1.00× means the property generates exactly enough to cover its debt payments and nothing else. Above 1.00× there is cushion; below it, the shortfall comes from somewhere other than the property.

That's the entire concept. It says nothing about appreciation, nothing about your other holdings, and nothing about how good the deal is. It answers one question: does this building carry this loan.

Net operating income is where deals are won and lost

NOI is gross rental income less operating expenses — taxes, insurance, management, maintenance, utilities you pay, and a realistic vacancy factor. It is not income less every cash outflow, and it excludes the debt service itself.

Two things reliably inflate it: using scheduled rent instead of collected rent, and leaving out the expenses that only show up annually. Both make the ratio look better on a spreadsheet and neither survives underwriting.

Debt service depends on structure, not just rate

The same loan amount at the same rate produces very different annual debt service depending on whether it amortises and over how long. Interest-only lowers the payment and raises the ratio; a shorter amortisation does the opposite.

This is why a deal that fails coverage at one structure can clear it at another. Changing the structure changes the denominator without changing the property at all.

Where DSCR stops being the right question

On a property that isn't stabilised yet, current DSCR measures a situation you're planning to change. A half-empty building underwritten on today's income will fail a coverage test that the same building passes twelve months after lease-up.

That's a case for underwriting the plan and the exit rather than the trailing twelve. It is not a case for pretending the current number is better than it is.

General information about commercial real estate financing. It is not legal, tax, accounting or investment advice, and it does not describe the terms available on any particular transaction.

A good deal shouldn't die waiting on a bank.

Tell us about the transaction. You'll get a straight answer about whether it fits — including a fast no if it doesn't.

When Banks Stall, Maverick Moves.

Submitting deal information does not constitute an application for credit. Nothing here is an approval, a denial, a commitment to lend, or an offer of credit. All financing is subject to underwriting, third-party reports and final credit approval.

Get My Deal Done